Fingram 2026-06-18 0
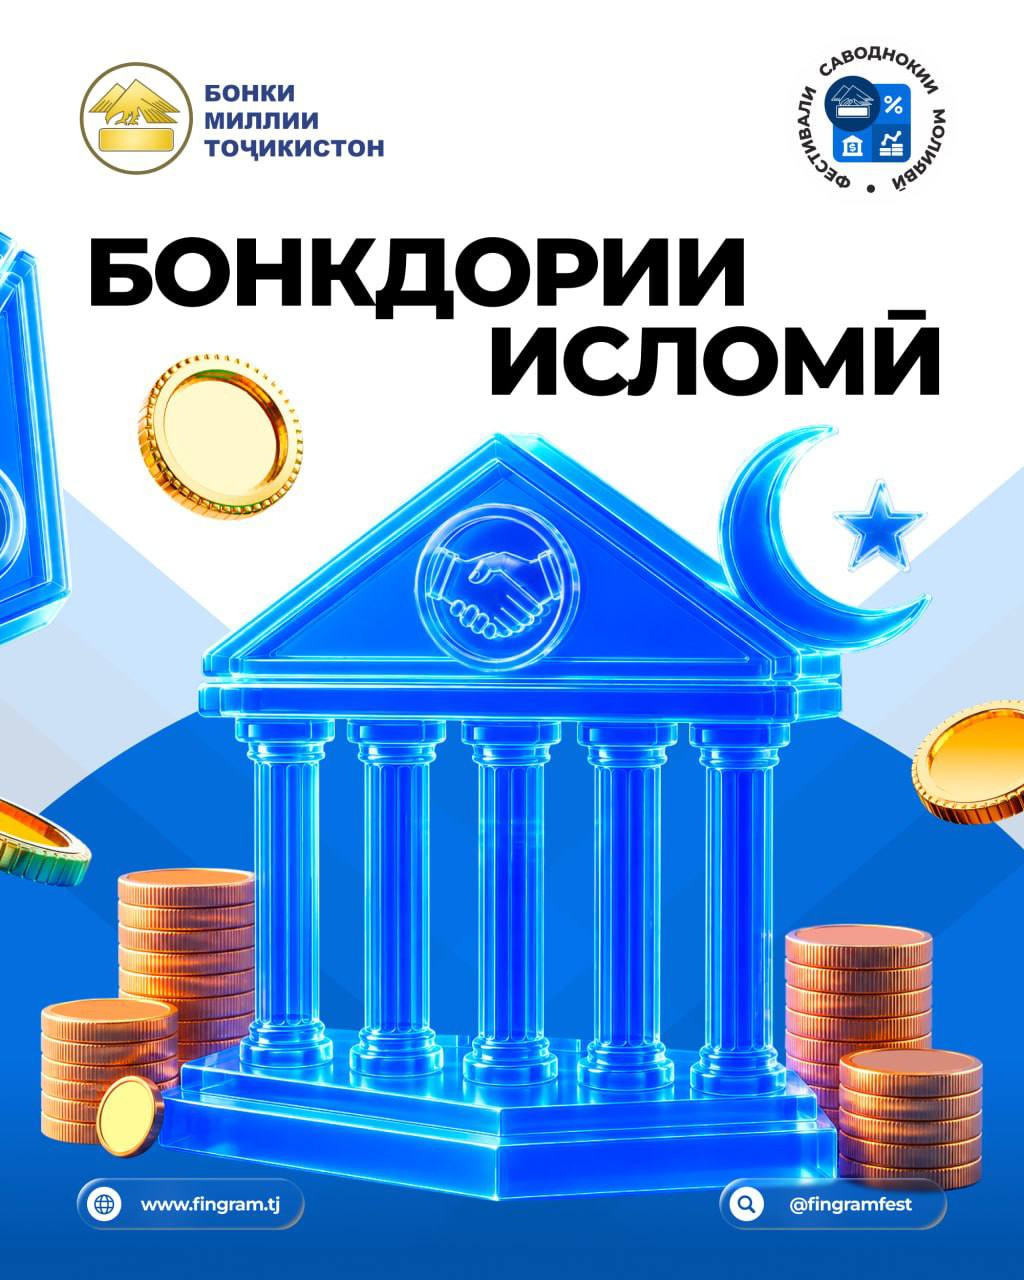
Islamic Banking in the Republic of Tajikistan
Islamic Banking in the Republic of Tajikistan
The legal and institutional framework for Islamic banking in the Republic of Tajikistan is established by the Law of the Republic of Tajikistan "On Islamic Banking Activities", which provides a favorable environment for the development of Islamic financial services in the country.
Currently, one Islamic bank and four Islamic banking windows operate in the Republic of Tajikistan. The total number of service outlets of Islamic credit institutions is 39, including 5 branches, 32 banking service centers, and 2 cash service points.
It should be noted that Islamic credit institutions operate under a distinct regulatory framework. Their regulation and supervision are carried out in accordance with the principles of Islamic finance, including the standards of the Islamic Financial Services Board (IFSB) and the Accounting and Auditing Organization for Islamic Financial Institutions (AAOIFI).
Accordingly, Islamic banking transactions are conducted in compliance with the principles of Islamic finance, Shariah requirements, and the above-mentioned international standards.
At present, Islamic credit institutions in Tajikistan offer customers the following Islamic banking products and services:
1. Murabaha – a cost-plus sale contract under which an Islamic credit institution purchases goods at the request of a customer and sells them at an agreed price consisting of the purchase cost plus a mutually agreed profit margin.
2. Mudarabah – a partnership contract in which one party (the investor) provides capital, while the other party (the entrepreneur) manages the investment using their expertise and labor. The resulting profit is shared between the parties in accordance with the terms of the agreement.
3. Qard Hasan – a benevolent, interest-free loan under which one party provides funds to another without any additional charge or profit, either on a repayable basis or for charitable purposes.
4. Ijarah – a leasing arrangement in which the lessor acquires equipment or other assets and leases them to the customer for temporary use or possession in return for rental payments over an agreed period.
5. Salam – a forward purchase contract in which the buyer pays the full purchase price at the time the contract is concluded, while delivery of the goods is deferred to a future date.
6. Ijarah Muntahia Bittamleek – a lease-to-own agreement under which the customer acquires ownership of the leased asset either upon the expiry of the lease term or progressively during the lease period, as specified in the contract.
As a modern component of the financial system alongside conventional banking, Islamic banking plays an important role in ensuring the sustainable and balanced development of the banking sector. By adhering to the principles of Islamic law (Shariah), it contributes to the diversification of financial services, mobilizes idle funds from the public, and strengthens financing for the real sector of the national economy.
Follow our page to learn more about Islamic banking products and the terms and conditions governing their use.
Please log in to leave a comment.


All comments